

Be honest: if someone asked you what a 2/1 buydown is, could you explain it? Most buyers can’t, and that’s a shame, because it’s one of the easiest ways to get a lower interest rate and a lower monthly payment when you buy a home.
When all anyone can talk about is interest rates, it’s time to get creative. So we teamed up with a local lender, Ethan Lane with Northpoint Mortgage, to break it down, and then show you what it looks like on a real listing.
So what is a 2/1 buydown?
A 2/1 buydown temporarily lowers your interest rate for the first two years of your loan. The cost is paid upfront at closing, and it’s often something buyers can ask the seller to cover as a concession, so the savings don’t have to come out of your pocket.
Here’s how it plays out on a 7.50% loan:
- Year 1: your rate drops 2 points, to 5.50%
- Year 2: your rate drops 1 point, to 6.50%
- Year 3 on: you’re at your regular 7.50% for the rest of the loan
That gives you two years of lower payments while you settle in, furnish the place, or wait to see if rates come down enough to refinance.
The real numbers on a local listing
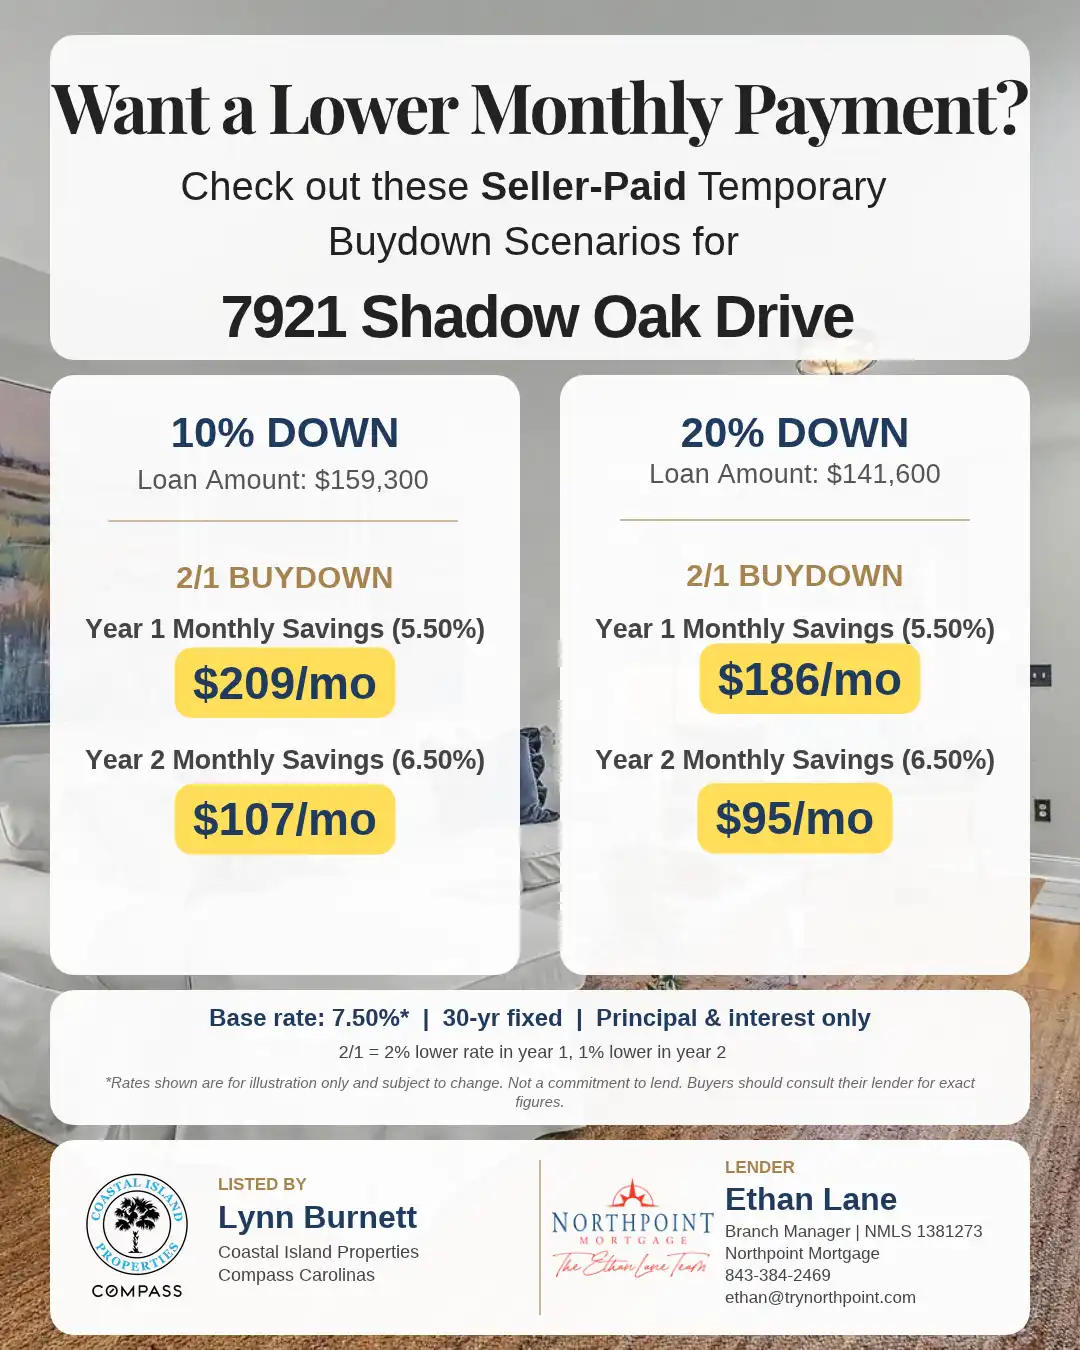
7921 Shadow Oak Drive is a 2-bed, 1.5-bath townhome in Oak Bluff, North Charleston, SC offered at $177,000. The seller is offering a 2/1 buydown on this one. Here’s what it could save you each month:
| Down payment | Loan amount | Year 1 savings (5.50%) | Year 2 savings (6.50%) |
|---|---|---|---|
| 10% | $159,300 | $209/mo | $107/mo |
| 20% | $141,600 | $186/mo | $95/mo |
With 10% down, that adds up to about $3,792 back in your pocket over the first two years.
The home itself is a turn-key slice of Lowcountry living: moss-draped oaks out front, an open, light-filled layout with luxury vinyl plank floors, and a private back patio made for morning coffee. You’re close to parks, shopping and dining, with an easy commute downtown or out to the beaches.
Who it’s great for
A 2/1 buydown is a smart fit if you:
- Are a first-time buyer who wants some breathing room in the first couple of years
- Expect your income to grow over the next few years
- Want a lower payment now and plan to refinance if rates drop
One thing to know: a buydown is temporary. Your payment steps up in year two and again in year three, so you’ll want to be comfortable with the full payment from day one. That’s exactly the kind of thing Ethan can walk you through.
Ready to see your numbers?
Curious what a 2/1 buydown could look like on the home you have your eye on? Reach out to us and we’ll connect you with a lender so we can run the numbers together!
Coastal Island Properties of Compass Carolinas, 843.883.4422 or Info@SCCoastalIslandHomes.com
Ethan Lane, Branch Manager, NMLS 1381273: 843-384-2469 or ethan@trynorthpoint.com.
Rates shown are for illustration only and subject to change. Based on a 7.50% base rate, 30-year fixed, principal and interest only. Not a commitment to lend. Buyers should consult their lender for exact figures.
Social Cookies
Social Cookies are used to enable you to share pages and content you find interesting throughout the website through third-party social networking or other websites (including, potentially for advertising purposes related to social networking).